Federal Court rules insurance companies must behave decently. That's a big deal
- Written by: Benjamin Koh, Honorary Associate, Faculty of Business, School of Management, University of Technology Sydney
It almost reads like a John Grisham novel.
Self-employed woman contracts cancer. Claims under her income-protection insurance policy. Insurer cancels the policy after investigation reveals omission of unrelated health condition (depression) on her original application. She is accused of acting in bad faith and threatened with having to repay the money (A$24,000) already received. Her story comes to national attention. A dramatic court battle ensues. Justice is finally served.
Last week just such a narrative concluded in the Federal Court, when chief justice James Allsop found TAL Life, one of Australia’s biggest life insurers, had breached its duty to act with “utmost good faith” by cancelling a sick woman’s income-protection policy through the questionable practice of “retrospective underwriting”.
The Federal Court case was initiated by the Australian Securities and Investments Commission in December 2019. This followed evidence from the banking royal commission in 2018 showing the lengths TAL went to in seeking to void insurance policies.
Justice Allsop ruled TAL’s actions – including not informing the claimant she was under investigation, reaching a wrong conclusion, failing to give her a chance to respond, and threatening to pursue her for money – lacked “decency and fairness”.
However, he did not agree with the corporate regulator that TAL’s actions amounted to false or misleading conduct. Guilt on that charge would have meant a fine.
The ruling carries no financial penalty, apart from TAL having to keep its end of the contract. The judgment is nonetheless significant. It puts insurance companies on notice about the use of retrospective underwriting, scrutinising insurance applications only when a claim is made, and covertly trawling through applicants’ medical and financial records to find any excuse to void the policy.
What is underwriting
Let’s briefly recap what insurance underwriting means.
It is the process of assessing an applicant’s risk and pricing a life insurance policy (which includes a policy such as income protection) accordingly.
If you have, for example, a history of hypertension, you have a higher risk of stroke. This is something an underwriter wants to know, to accurately assess your actuarial risk. They may increase the premium you pay, or exclude from the policy claims for strokes, or decline cover altogether.
Insurance application forms typically require you to declare “yes” or “no” to a list of the most common medical conditions or circumstances, with an open-ended question about other “relevant” conditions.
Usually the underwriting process is straightforward. Insurers accept declarations in good faith, and approve applications (and collect the premiums) as quickly as possible.
 Rubber-stamping documents does not happen literally, of course, but it is a powerful visual metaphor for the process of approving an application with insufficient due diligence.
Shutterstock
Retrospective underwriting
But that changes when you make a claim.
Then insurers are unwilling to accept anything in good faith. They typically require you to authorise access to your financial and medical records, including records you may not have seen – such as your doctor’s notes.
A doctor might note observations about a patient seeming depressed. It’s not an explicit diagnosis. But an insurer may retrospectively consider this undisclosed evidence of “depression”.
Finding “relevant” information not declared in the original application gives the insurer an excuse to “retrospectively underwrite” the policy – determining what policy it would have offered (if at all) had that information been known.
Retrospective underwriting usually favours insurers as it is done with the knowledge of an existing claim. The federal Insurance Contracts Act allows insurers, under certain conditions, to cancel policies within three years of inception due to relevant non-disclosures or misrepresentations in applications.
Read more: Very risky business: the pros and cons of insurance companies embracing artificial intelligence
TAL at the royal commission
Appearing before the banking royal commission in September 2018, TAL senior executive Loraine van Eeden agreed the company’s approach had lacked empathy. She acknowledged it was wrong to not tell the claimant she was being investigated, and wrong to not give her a chance to respond to the reason for the retrospective underwriting.
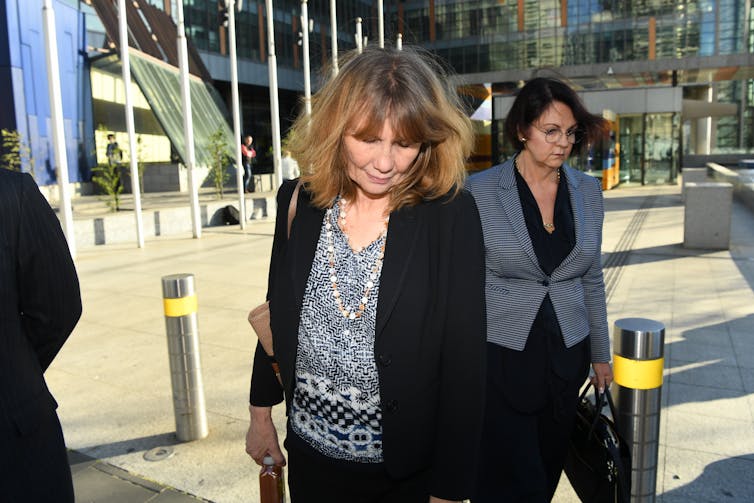 TAL senior executive Loraine van Eeden after appearing before the royal commission into misconduct in the financial services sector on September 13 2018.
James Ross/AAP
TAL had approved the woman’s income protection insurance in October 2013, asking detailed medical questions, including those of mental health. In mid-December she was diagnosed with cervical cancer. She lodged her policy claim on January 3 2014.
TAL accepted the claim on 7 January and made monthly payments until May. In June it cancelled the policy, on the basis her medical records revealed undisclosed mental health issues it said would have changed the initial underwriting. Perhaps, one suspects, not offer cover. TAL did not suggest she was dishonest.
Practical implications
In our experiences it is not unusual for insurers to use a claims process to retrospectively underwrite. Often claimants only become aware of this when they’re told there is information giving the insurer the right to cancel the policy.
Under the life insurance industry’s voluntary Code of Practice, insurers are meant to explain why they’re requesting information relevant to a claim.
The corporate regulator and consumer advocates have long held concerns the three-year window to cancel policies encourages insurers to go on “fishing expeditions”.
No more spying
Since January 1 the rules giving insurers three years to cancel a policy have been tightened – one of the 27 of 76 recommendations from the banking royal commission the federal government has implemented.
Insurers now may only “avoid a contract of life insurance on the basis of non-disclosure or misrepresentation if it can show that it would not have entered into a contract on any terms”.
Read more: Ideology triumphs over evidence: Morrison government drops the ball on banking reform
The Federal Court ruling puts life insurers on further notice. It clarifies what the “duty of utmost good faith” required by the Insurance Contracts Act means.
They don’t need to behave dishonestly to breach that duty. Not meeting community expectations of decency and fairness is enough. That doesn’t leave much room for lesser signs of excessive suspicion, let alone “deep-dive” operations to dig for dirt. That’s all but been declared illegal.
Authors: Benjamin Koh, Honorary Associate, Faculty of Business, School of Management, University of Technology Sydney