NZ's unemployment insurance scheme will be the biggest welfare shakeup in generations – is it justified?
- Written by: Simon Chapple, Director, Institute for Governance and Policy Studies, Te Herenga Waka — Victoria University of Wellington
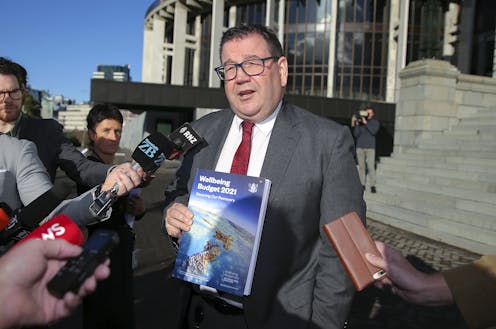
When Minister of Finance Grant Robertson announced in this year’s budget that his government was developing a social unemployment insurance scheme, people could have been forgiven for seeing this as largely positive.
Robertson suggested the scheme would be “ACC-like” and hinted it would pay low and middle-income earners who lost their jobs about 80% of their previous earnings (up to some maximum cap) for somewhat less than a year.
What’s not to like? We argue there is actually more than a little cause for concern, not least because there has been a worrying lack of public consultation on policy alternatives.
Furthermore, there’s the risk of creating a two-tier welfare system, given those eligible will be people with a stable employment history and payments will be related to their pre-redundancy earnings.
Private insurance problems
In our just published Policy Quarterly paper we ask what problems a social insurance scheme might solve, and we conclude the case for one is not persuasive.
To see why, it helps to look at how existing private insurance markets work. People generally want to protect themselves from things like job loss, illness, death, theft or destruction of property – so they buy insurance policies.
However, there are two problems with the private insurance market, meaning they under-provide relative to people’s real need.
Read more: Why is New Zealand's Labour government trying to push through a two-tier benefit system?
The first problem is called “adverse selection”, meaning people choosing to buy insurance have better information about the risks facing them than insurance businesses do, and no good reason to disclose that information.
To protect themselves from this, insurance companies set premiums higher. In turn, due to the costs, this leads to people being under-insured. Ultimately, society’s best interests aren’t met.
There’s also the problem of “moral hazard” – if a person has insurance they may take on more risk, without the insurer knowing exactly which customers are adopting riskier behaviour.
Again, insurance companies set higher premiums and people are generally under-insured. And again, this isn’t in society’s best interests.
What would justify change?
These market failures mean there is potential for well-designed government interventions to meet the social interest. In particular, making everyone join a social insurance scheme would fix the adverse selection problem.
But a compulsory social insurance system also expands the scope for moral hazard. People might change their behaviour to increase their eligibility for an insurance payout. They might take on jobs with higher redundancy risks, or be less motivated to look for work, because the consequences are now less severe.
Read more: 10 ways New Zealand employers can turn the 'great resignation' into a 'great recruitment'
Market failure isn’t the only possible rationale for a compulsory social insurance scheme, however. Economies of scale, for example, could allow the government to reduce the cost of such a scheme – subsidising the private sector to lower premiums would be an alternative.
Finally, there is the paternalistic justification: if people are unwilling, financially unable or simply too shortsighted to insure themselves, the government can do it for them.
What is already working?
But the government also needs to consider what other kinds of insurance already exist and are working. A (now dated) study from 2012 estimated that one in six New Zealand households had private income protection of some sort for sickness or unemployment.
Of course, there is already the working age welfare system to mitigate the risks of unemployment. Informally, as well, people insure against job loss by saving, upskilling, accumulating annual leave and reducing household costs.
Double-income, couple households have a form of in-built insurance in each other, and wider families often provide for one another when a person loses work.
Read more: Are low-paid jobs really a stepping stone to better pay? A new study suggests it’s not that simple
Some workers will already have redundancy provisions in their employment contracts. A decade ago, the OECD reported more than half of displaced workers in New Zealand had an average redundancy entitlement of over NZ$28,000. That’s not inconsiderable insurance.
Similarly, the student loan scheme funds education and training, including re-skilling if one is made redundant. What’s more, the three million plus people with KiwiSaver accounts (which had an average value of $26,000 in 2021) can access the funds in emergencies, including unemployment.
Lastly, an effective monetary and fiscal policy that keeps unemployment low and stable is likely to eliminate much of the need for an unemployment insurance system.
Reasons to be cautious
While always imperfect, these substitutes go a considerable way to mitigating the failure of the primary private insurance market. Policymakers advocating for state-provided social insurance need to ask the question: does a social insurance solution add anything to this existing mix?
If it turns out there are gaps in the current system, advocates of social insurance must also consider:
such a scheme may simply be substituting for one or several of the existing solutions, which would then reduce if the scheme were introduced
reforming and improving what already exists may be preferable in terms of cost, effectiveness and equity than introducing an entirely new system
there may be implications for both equity and erosion of the core welfare system of creating a separate, higher tier of assistance for some.
Read more: Young and ethnic minority workers were hardest hit at the start of COVID, but not anymore
Too many unknowns
Like what it seeks to replace, social insurance will itself be an imperfect substitute for the private insurance market because it’s a one-size-fits-all solution with no allowance for human diversity.
And it creates significant incentives for both employers and employees to game the system by shifting the costs of employment disputes (such as performance management and personal grievances) onto third parties – other levy payers.
The behavioural responses to such a scheme and thus the size of the policy gamble being taken are anyone’s guess.
Failures in the policy process to ask and answer these kinds of questions mean we remain unpersuaded about the social insurance conclusions to which the Labour government has apparently jumped.
Authors: Simon Chapple, Director, Institute for Governance and Policy Studies, Te Herenga Waka — Victoria University of Wellington