
Google AI


Modern Australian

Australians need good financial advice more than ever to pay for soaring interest rates. Here's how to get it

  • Written by: Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University
Australians need good financial advice more than ever to pay for soaring interest rates. Here's how to get it

Hundreds of thousands of us who took out fixed-rate mortgages in 2020 and 2021 are about to be hit with massive increases in payments.

After nine successive interest rate increases and at least two more to come, even those of us on variable rates will soon be paying as much as A$1,000 a month more.

With such an uncertain economic outlook, should we switch our super fund’s investment strategies from “growth” to “conservative”? Should we rent rather than buy while home prices fall?

We need answers to our financial questions – but they’re now much harder to get.

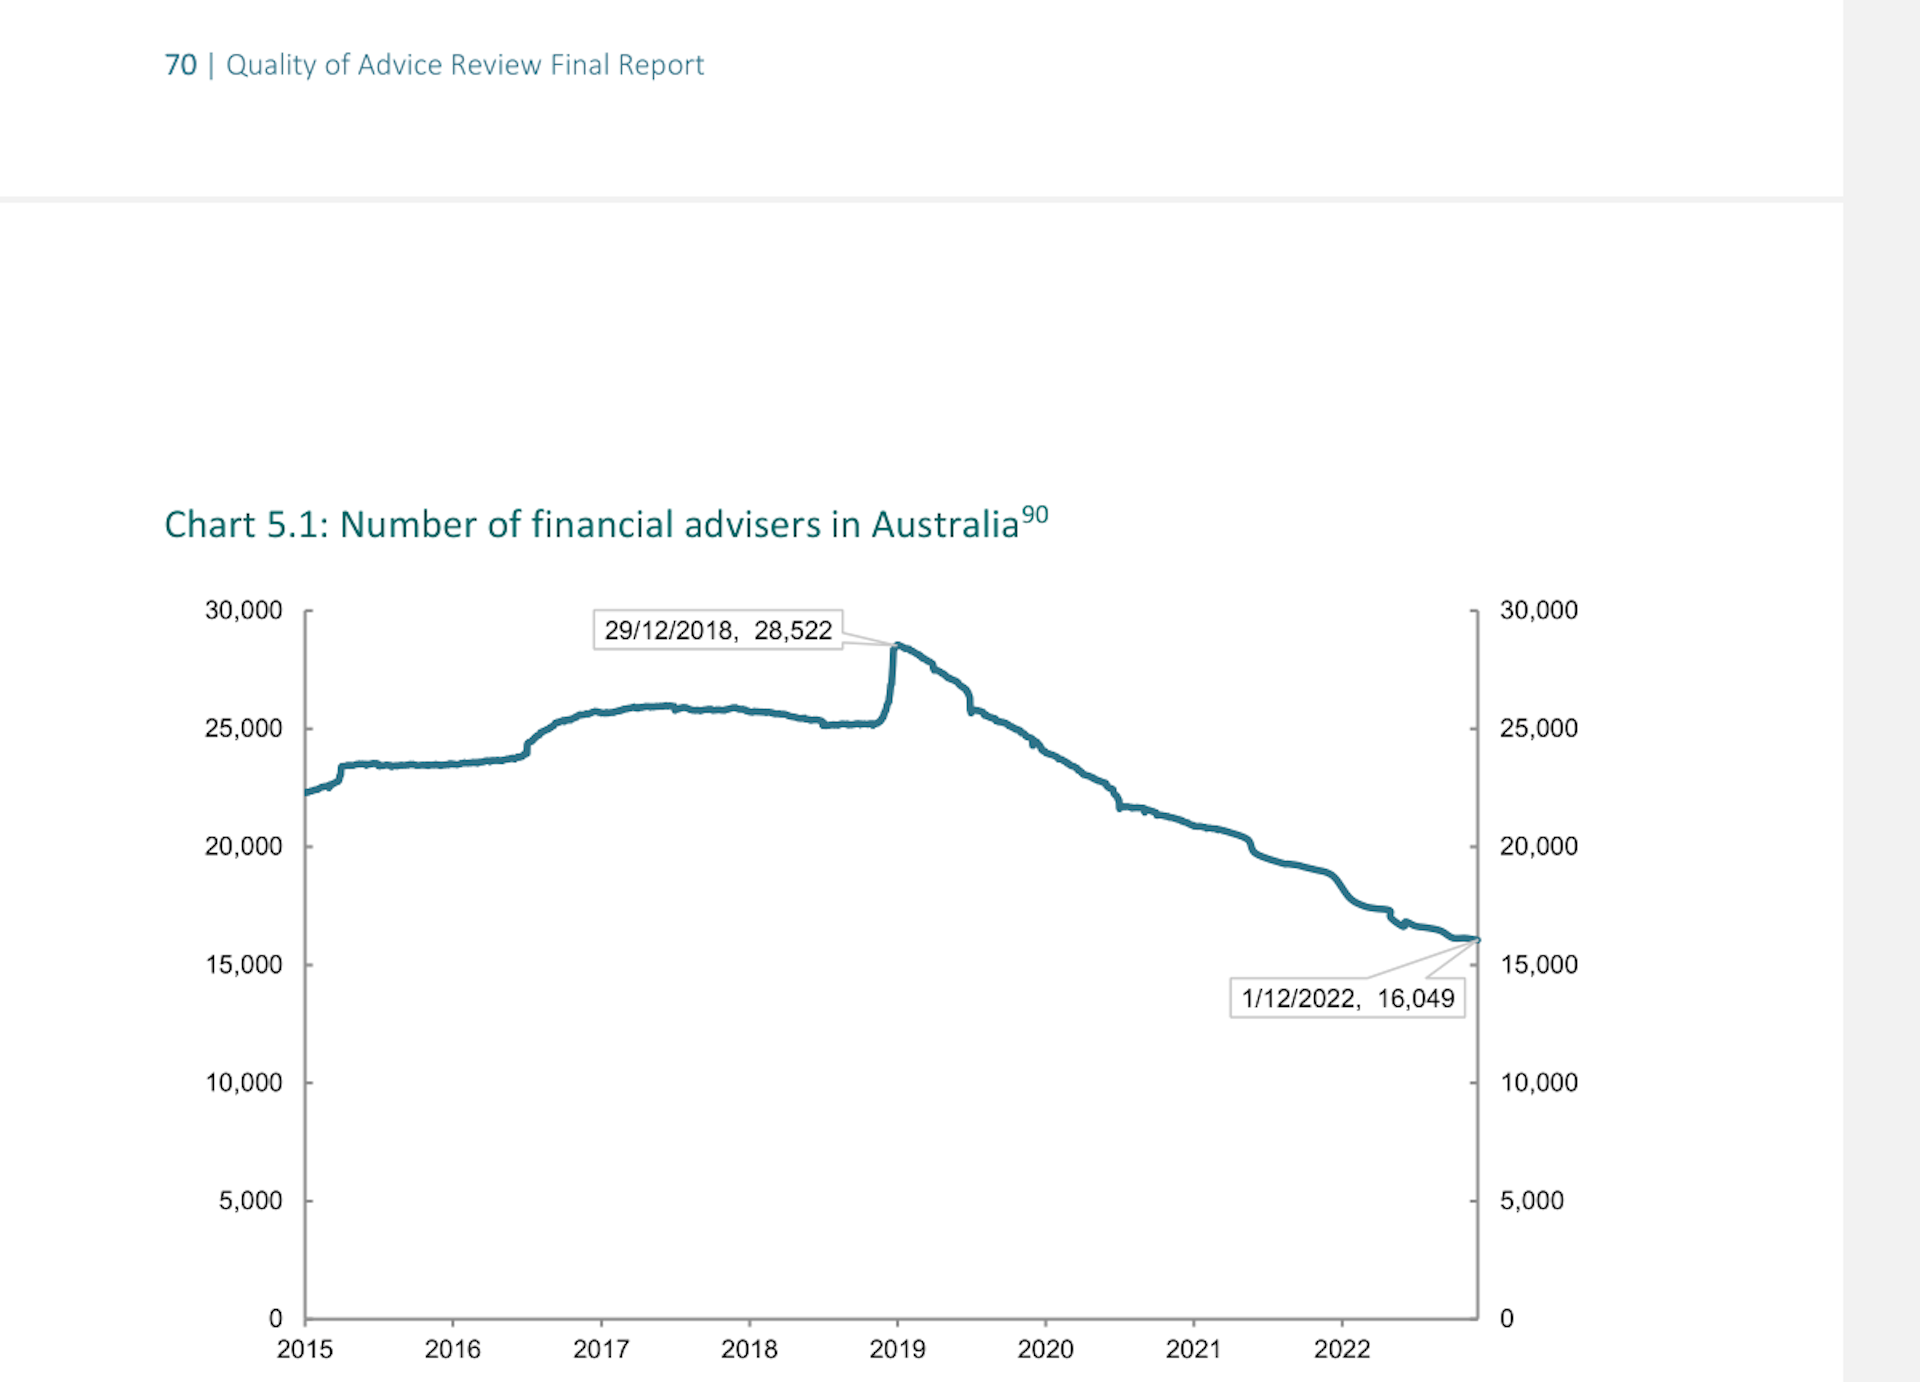
Five years ago, Australia had 28,000 financial advisers. Today there are 16,000. That’s according to a review of financial advice commissioned by the previous government and released by the Albanese government last week.

Thousands of advisers are leaving the industry each year. The ones that remain are charging far more than they used to – $3,710 is said to be common, up 48% in five years, and enough to turn many people away.

So how did it come to this? And what does the new report recommend we do to make it easier for more Australians to get good, more affordable financial help?

Fixing rorts, where even dead people paid a price

This is a story about how Australia, under successive Labor and Coalition governments, let aiming for what’s perfect get in the way of what’s good. Up until I read the Quality of Advice Review last week, I was guilty of doing it too.

For years, I argued we should make financial advice perfect: delivered by genuinely professional advisers, who weren’t receiving kickbacks from firms wanting access to our money. I also argued we should pay for that advice in full upfront, because, whatever the cost, the advice will save us money in the long run.

We needed to do something. Back before a series of explosive Four Corners reports and the 2019 Hayne royal commission into the financial services industry, advisers and the funds they pushed us towards sucked money out of our accounts and presented us with options that made money for them – rather than us.

Read more: Royal commission scandals the result of poor regulation, not literacy

The consequences were shocking. Dead people were being charged for financial advice, and even for life insurance. Gym instructors and other “introducers” were used to lure people into products that charged unnecessarily high fees.

The professionals we now call investment advisers used to be called insurance salesmen. They were paid through commissions to beguile us into signing up for products that charged high fees and paid them high ongoing commissions.

Unintended results of tougher standards

Ahead of the Hayne royal commission, things began to change.

The Rudd Labor government outlawed commissions and introduced legislation requiring advisers to “place clients’ interests ahead of their own”. After winning government, the Coalition tried to undo the changes, before adopting just about the lot after Hayne reported.

It’s now illegal for financial advisers to accept commissions (although mortgage brokers and people who sell insurance still can) and illegal to offer advice that isn’t in the “best interests” of the customer taking almost everything into account. This makes it all but impossible for bank tellers and super funds to offer advice.

So I have been having second thoughts about the arguments I once made for no commissions, best interests, and lots of disclosure documents – especially after reading the Quality of Advice Review. Ironically, its release was largely drowned out by coverage of Australians’ growing financial stress.
The report’s author Michelle Levy is a senior lawyer and expert on superannuation, life insurance, distribution and financial services law. As well as being a partner at Allens, she’s also a parent – and knows more than most how vile predatory financial advisers can be. During the royal commission, we heard about a man with Down syndrome who was signed up for life insurance over the phone, even though he lived on a pension, had no dependants and could not afford the premiums. In her review, Levy discloses that she has a daughter who, “like this gentleman”, lives with a disability and has bank accounts, but does not know the difference between $10 and $1,000, does not know how to use a credit card, or what superannuation is. Levy writes that her daughter ought to be able to rely on her bank and super fund to assist her. She says by stopping firms from providing advice that isn’t perfect, we’ve inadvertently stopped our financial institutions from providing advice that is “good”. We have made it hard for human beings to help each other. Why ‘good’ might be a better benchmark than ‘best’ So Levy wants to allow super funds and banks to offer advice which is “good” but isn’t comprehensive, in the same way as sales assistants are able to offer advice on clothes and mechanics are able to offer advice on cars. Good advice does not mean “okay advice” or “good enough” advice, she says. It is unlikely to be good advice to recommend a poorly performing superannuation product. It will not be good advice to recommend that a person who is unable to pay their mortgage open a term deposit. If the advice isn’t good, the full force of the existing law will come down on the person who provides it (the maximum penalty for an individual is $1.11 million). But it needn’t be comprehensive; not every piece of financial advice needs to be a lifetime plan. What Levy is proposing, and what the government is now considering, is more subtle than what we are doing at the moment – which is simply banning self-interested parties from giving advice. Levy wants to allow the self-interested to give advice, while ensuring it “also serves the interests of their customers”. In the meantime, if you need financial advice, the National Debt Helpline is one of a number of places that can help. You can request a free, confidential meeting with a financial counsellor on 1800 007 007. Read more: Why would you dump a requirement for financial advisers to give advice that's in their client's best interests? Authors: Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

Read more https://theconversation.com/australians-need-good-financial-advice-more-than-ever-to-pay-for-soaring-interest-rates-heres-how-to-get-it-199739

Common Skin Concerns and Treatment Options Available in Melbourne

Skin concerns can develop gradually or become noticeable following changes in age, lifestyle, sun exposure or hormonal factors. Pigmentation, rednes...

Why a Code-Compliant Home Can Still Feel Uncomfortable

When people build or renovate a home, they usually expect that meeting current building requirements will also produce a comfortable place to live. ...

Breach of Contract in Business: What Are Your Options?

Contracts are essential to business relationships. They establish expectations, allocate responsibilities and provide a framework for delivering goods...

How Pest Control Companies Can Rank for the Problems Customers Search First

Introduction SEO for Pest Control needs to start with the customer’s problem. Most people do not search for pest services in a neat or technical wa...

What Are the Benefits of Renovating an Older Home in Sydney?

Sydney has plenty of character homes, from Federation cottages to mid-century brick homes. Renovating rather than rebuilding can preserve what makes t...

Pool and Deck Design: How to Plan the Perfect Outdoor Living Space for Your Sydney Home

For many Australians, the backyard is where life happens. Summer barbecues, weekend swims and long evenings outdoors are all part of the lifestyle, ...

Is Solar Pool Heating Worth It? What Sydney Homeowners Should Know

There's nothing quite like a backyard pool on a hot Sydney day. But once autumn rolls in, many pools sit unused for months because the water is simp...

Planning a Luxury House Move: A Week-by-Week Timeline for Prestige Sydney Homes

Selling or buying a prestige home is a major milestone. Whether it's a waterfront residence in Birchgrove, a grand Federation home in Haberfield or ...

Downsizing or Upgrading Your Caravan? Here's How to Sell It Without the Hassle

Selling a caravan can feel like a major task, especially when you are unsure about its value, paperwork, or how to find a buyer. Whether you are dow...

The Best Overseas Adventure Holidays for Australians Who Love the Outdoors

Australia offers no shortage of incredible outdoor experiences, but sometimes the best way to satisfy your sense of adventure is to head overseas. A...

Cape Town Wine Shuttle: Winelands Tasting & Tours

Embark on an unforgettable journey through the picturesque Cape Winelands, where world-class wines and breathtaking scenery await. Our Cape Town Win...

Metal Fabrication: Choosing Metal Fabrication Melbourne Services for Custom Projects

What Modern Metal Fabrication Involves From individual components to complete structures, metal fabrication brings together processes such as desig...

Why Giant Rats Tail Grass Keeps Coming Back After Spraying

Giant Rats Tail Grass (GRT) is one of the most frustrating pasture weeds for farmers and lifestyle property owners. You spray an infested area, see th...

When Custom Cardboard Boxes Make Sense for Your Business

Custom cardboard boxes can be useful when a standard carton does not fit a product, packing method or presentation requirement particularly well. A ...

Full-Height vs. Pop-Top Caravan: Which Is Better for Family Travel across WA?

A pop-top caravan is an excellent choice for travellers who want the comfort of a caravan without committing to a larger, bulkier setup. With a lowe...

Bottle Label Printing: Key Factors for a Professional Finish

Why the Printing Method Matters When businesses need packaging or printed containers developed for a particular application, the right supplier can m...

Virtual Livestock Fencing and GPS Tracking: Improving Visibility Across Cattle Properties

What Virtual Livestock Fencing Means for Modern Cattle Management Managing cattle across extensive properties requires more than knowing where anim...

Sydney Pawnbrokers Explained: How Hocking Your Car Actually Works

Sometimes you need cash, and you need it soon. If you own a car, you may already have a way to get it. That's what people mean when they say they've...