
Google AI


Modern Australian

The housing game has changed – interest rate hikes hurt more than before

  • Written by: Joey Moloney, Senior Associate, Grattan Institute
The housing game has changed – interest rate hikes hurt more than before

The Reserve Bank has lifted the cash rate for the second time in two months, this time by 0.50 points to 0.85%.

It won’t be the last such hike. Forecasters expect the cash rate to hit 2.5% by the end of next year. This would lift the typical variable mortgage rate to near 5%.

Cue the claims that the new generation of borrowers are entitled – they don’t know how good they’ve had it with such low rates.

But the refrain misses the full story. High house prices have changed the game, making it much harder for today’s borrowers.

It is true that even a mortgage rate of 5% is well below the peak of about 17% earlier generations paid at the start of the 1990s.

But the impact of those high rates on overall mortgage interest payments as a share of income was modest, because house prices were much lower then, and mortgages were much smaller.
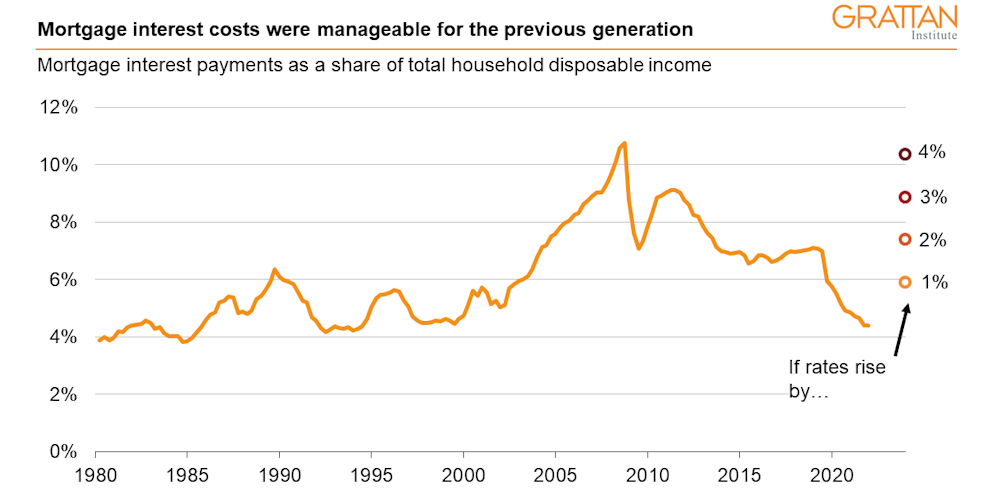
Projection is for December 2023. It uses the average mortgage interest rate as at December 2021 and assumes household debt-to-income ratio is stable at December 2021 levels. RBA Tables E2 and F6; ABS National Accounts; Grattan analysis.

Typical house prices used to be about four times incomes. Now they’re more than eight times incomes, and more in Melbourne and Sydney.

This has meant that for any given mortgage rate, the share of income taken up by mortgage payments is much, much higher.
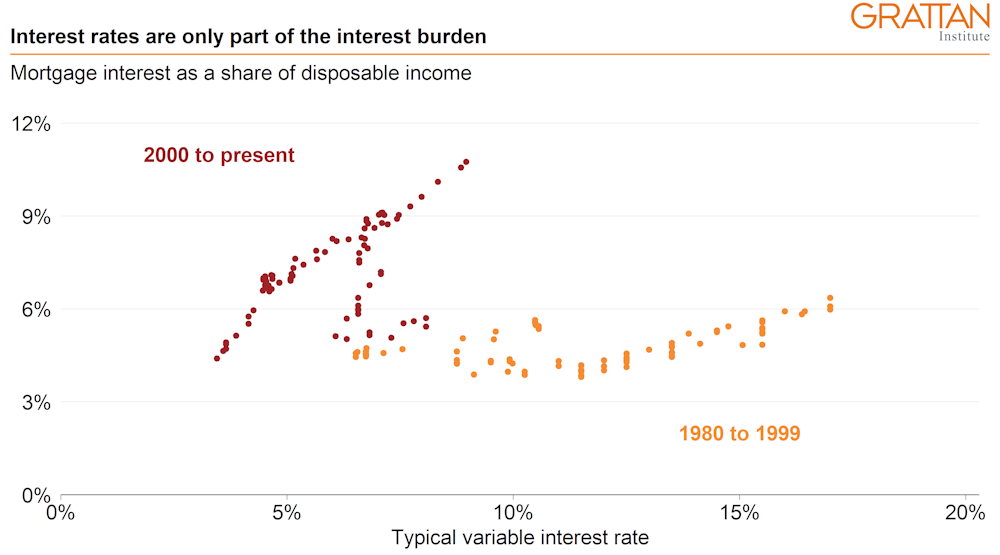
Each dot represents a 3-month period. Source: RBA Tables E2 and F6

If you have a small loan with a high rate, all you need is a cut in rates, some inflation and decent income growth, and your mortgage burden can fall sharply.

That’s how it was for borrowers in the 1990s. High rates stung, but not for long.

Borrowers in the 1990s who started out devoting more than 30% of their income to paying off a mortgage found themselves devoting just 12% by the time the loan was halfway through.
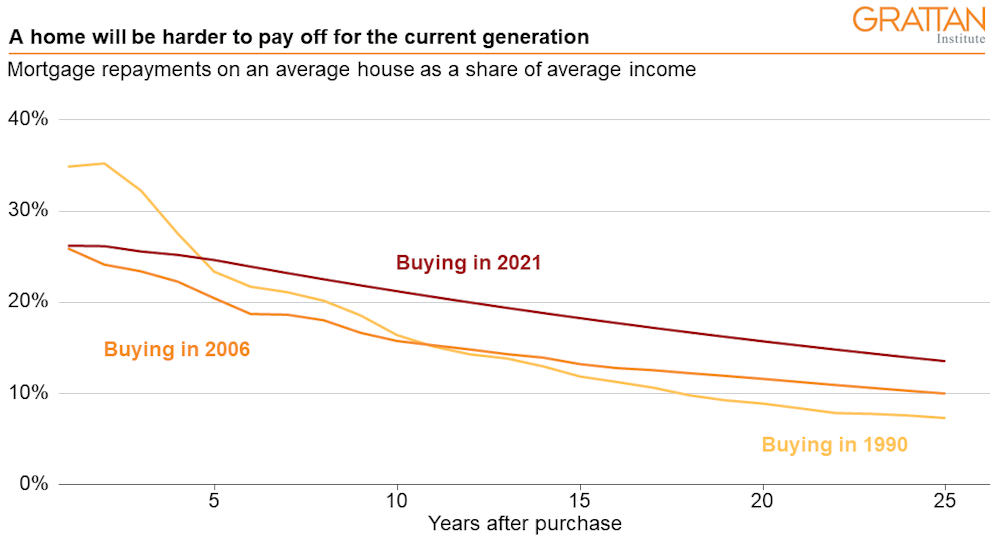
Assumes 80% LVR 25-year loan on average house price in year of borrowing, taken from Yates (201 1) for pre-2010, and ABS thereafter. No lenders mortgage insurance. Income is gross disposable income from ABS National Accounts. Historical interest rates are rolling 3-year averages of standard variable rates (discounted from 2004). Projected interest rates are average of past 10 years. Projected income growth is 3%. Sources: ABS National Accounts and Residential House Prices; RBA Table F6; Yates (2011); Grattan Analysis

It’s different if you’ve borrowed recently.

If you’ve taken out a big loan at today’s ultra-low interest rates, there’s only one way your mortgage payments can go – and that’s up.

Even if mortgage rates stabilise at around 5% – which is implied by some of the things the Reserve Bank governor has said – and wages grow faster than they have for a decade, the mortgage burdens of millennials who’ve bought houses recently won’t much decline.

The extraordinary increase in house prices and debt means mortgage rates of 7% would be as painful to borrowers today as rates of 17% were decades ago.

It’s a common barb that newer generations are struggling with home ownership and housing costs because of profligate spending, on smashed avos and the like.

Read more: Paying off a home loan used to be easier than it looked. It's now harder

But millennials spend less of their incomes on “discretionary” items – such as alcohol, clothes and household services – than people of the same age did decades ago.

What millennials are spending much more on is housing, simply because houses are so much more expensive.

So as the Reserve Bank continues to increase rates, it’s important to keep in mind that comparisons between then and now miss the full story.

Skyrocketing house prices have changed the game. For millennials, even historically small increases in interest rates will hurt.

Read more: Expect the RBA to go easy on interest rate hikes from now on – we can't afford rates to climb as steeply as the market expects

Authors: Joey Moloney, Senior Associate, Grattan Institute

Read more https://theconversation.com/the-housing-game-has-changed-interest-rate-hikes-hurt-more-than-before-184553

Why the Spring School Holidays Are a Great Time to Visit Coffs Harbour

The spring school holidays are a good time to spend a few days on the Coffs Coast. The weather is starting to warm up, there is plenty to do outdoor...

What to Do When an Older Car Is No Longer Worth Keeping in Melbourne

Ever looked at another repair quote and wondered whether your old car is still worth the trouble? It is a common turning point for Melbourne motoris...

Your Baby's First Year: A Local Guide to Feeding, Sleep, and When to Get Extra Support

Ask ten parents in a Brisbane mothers' group how their baby is feeding or sleeping, and expect ten different answers.  Someone's baby sleeps throug...

Kitchen and Laundry Makeover Ideas That Don't Require a Full Renovation

Full kitchen renos are expensive — and most people don't actually need one.  They need the kitchen to stop looking like it's stuck in 2009, or they...

How Technology Is Reshaping the Modern Australian Commercial Kitchen

The commercial kitchen has always been shaped by technology. Refrigeration changed how ingredients could be stored, modern ventilation transformed k...

The Number on a Roller Blind Fabric That Nobody Explains

Somewhere in the fabric book, next to the colour name, there is a percentage. Three per cent. Five per cent. Ten per cent. Nobody explains it, most c...

What’s Trending in Men’s Jewellery This Father’s Day!

Finding a Father’s Day gift that feels personal, stylish and genuinely wearable is not always easy. While socks and novelty mugs have traditionally ...

Road Signs: Understanding Their Role in Clear and Effective Signage

Effective signage and display hardware can help businesses communicate information, promote products and organise customer or visitor movement. Road...

Bottle Label Printing: Key Factors to Consider Before Your Next Packaging Run

Effective packaging begins with understanding the product, bottle material, artwork and production requirements when planning bottle label printing. H...

Planning a Long-Distance Move With Interstate Movers Melbourne

Moving between states involves more planning than a typical local relocation. Along with packing and transporting household belongings, you need to...

Understanding the Role of an I/O Controller in Industrial Automation

Modern industrial systems depend on accurate communication between sensors, machines and control systems. An I/O controller can help manage this commu...

How the Right Mining Hose Supports Demanding Operations

Mining environments place considerable demands on equipment used for material transfer, water management and processing. Hoses operating in these co...

Simple Ideas for Making Social Gatherings More Memorable

We have all been to those parties where everyone just stands around the kitchen island, staring at their phones, waiting for someone else to make a mo...

Outdoor Wall Lights: Improving Exterior Lighting Around Your Home

Lighting can influence how a room looks, feels and functions, so the right fitting should be selected according to both appearance and practical req...

Commercial Office Cleaning: Combining Routine Office Cleaning With Melbourne Service

Keeping a workplace clean requires a service that can accommodate everyday tasks as well as the particular needs of the business. Professional comme...

Caravan Sales in Queensland: How to Find the Right Caravan for Sale QLD

Caravan ownership is about more than having somewhere to sleep while travelling. For many Queenslanders, it is one of the best ways to explore regio...

What Sir Walter Buffalo Turf Actually Costs in 2026 (And Why Quotes Vary So Much)

Two quotes landed on a Hills District homeowner's kitchen table last spring for the exact same 80-square-metre backyard. One said $12 a metre. The o...

Nearly 1,300 NSW Hospital Beds Are Occupied By People Who Are Ready To Go Home

1,276 people in NSW hospitals have been medically cleared for discharge but remain in hospital because they're still waiting for NDIS or aged care sup...