
Climate change is already putting the heat on insurance companies – Auckland's floods could be a turning point
- Written by: Michael Naylor, Senior Lecturer in Economics, Massey University
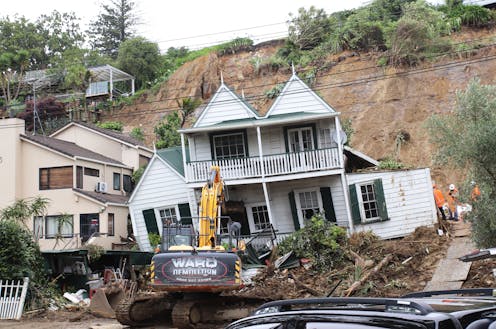
The clean-up from Auckland’s devastating floods last week is just beginning but insurance companies will need to start thinking about what the record-breaking weather event will mean for future coverage.
Over 24 hours, 249mm of rain fell across the Auckland region – well above the previous record of 161.8mm. Around 5000 homes were damaged across 25 suburbs, with more than 100 properties declared uninhabitable in the aftermath of the storm.
In the short term insurers have needed to provide support according to individual policies – for some this will include accommodation support while homes are uninhabitable, as well as assessment of final payouts.
But in the longer term insurers will now need to consider whether parts of Auckland will become significantly more expensive to insure. In the worst case scenario, the weekend’s floods might mean some sections of the city become too expensive to insure by mainstream insurance companies.
A small army of assessors and builders
Generally, New Zealanders are sufficiently covered by home insurance, with banks requiring basic house insurance as a requirement for mortgages. However, the full extent of the coverage will depend on individual policies.
The first hurdle to payout will be getting properties assessed in a timely manner. Insurance companies will need to send assessors to tally the damage, estimated to be “many millions” by Prime Minister Chris Hipkins.
But timely assessment and rebuilding is going to butt up against two broader issues: the ongoing skills shortage in the building industry and a shortage of materials.
Insurers are going to need to find enough qualified people – builders, for example – to assess the damage. Many of the seriously damaged properties will also need to be rebuilt from the ground up, placing further pressure on the construction sector.
Predicting damage from climate change
While insurers will first be focusing on getting the damaged properties assessed, there is a larger looming problem: climate change.
The first national climate change risk assesment, published in 2020, identified 675,500 New Zealanders as living in areas already prone to flooding. A further 72,065 were living at risk if some of the most dramatic effects of sea level rise hit.
It’s clear we have suburbs and even towns where, in hindsight, homes shouldn’t have been built.
Insurers are also facing issues with setting premiums. Currently, insurance premiums are based on the cost and livelihood of past events. Climate change makes this information dubious and the future insurance cost of climate change speculative.
Internationally, insurance companies are now investing millions in research to better understand the risk coming from adverse weather events related to climate change.
If climate change means these events become more common, New Zealanders with homes in high risk areas could see substantial spikes in premiums. Increasingly, the trend is for premiums to be calculated house by house, with neighbouring properties ending up paying different premiums based on risk to flood and earthquake damage.
Insurance companies could also decide that some houses or areas are just not worth the risk – as IAG has done for some properties in Wellington due to the earthquake risk – leaving home owners seeking insurance from special underwriters. This will inevitably carry significant extra cost.
The impact of climate change on premiums is not hypothetical. Last year, Tower became New Zealand’s first insurer to introduce a new pricing model based on individual homes’ risk of flooding. In a significant shift from traditional practice, the risk assessment was also made public. Other insurers are expected to follow.
Targeting LIM reports
Insurance companies aren’t just making their own assessments public. Insurers are also supporting government efforts to require councils to include significant risks on the Land Information Memorandum (LIM) reports of individual properties.
Last year, the Local Government Official Information Amendment Bill was introduced to parliament, setting out requirements for councils to make LIM reports clear and concise. The bill, which is currently open for public submission, requires councils to provide clearer information about risks like flooding and earthquakes.
Some risks – like a home sitting at the top or the bottom of a cliff, or along the coast – are obvious to potential buyers. But including the less obvious threats, like inadequate local drainage, in the LIM report could help people reduce their long-term risk when buying a home.
These initiatives go against the shorter term interests of some property owners, who believe that including potential – but not certain – risks on a LIM report will significantly reduce the sale value of their properties.
New Zealand insurers are not alone in having to change how they calculate premiums and how they manage risk. Globally, insurance companies are discussing the long-term impact of climate change on their business. Auckland’s recent flooding shows this issue is not a matter of potential risk, but rather a tangible reality.
Authors: Michael Naylor, Senior Lecturer in Economics, Massey University