
Google AI


Modern Australian

Australians need good financial advice more than ever to pay for soaring interest rates. Here's how to get it

  • Written by: Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University
Australians need good financial advice more than ever to pay for soaring interest rates. Here's how to get it

Hundreds of thousands of us who took out fixed-rate mortgages in 2020 and 2021 are about to be hit with massive increases in payments.

After nine successive interest rate increases and at least two more to come, even those of us on variable rates will soon be paying as much as A$1,000 a month more.

With such an uncertain economic outlook, should we switch our super fund’s investment strategies from “growth” to “conservative”? Should we rent rather than buy while home prices fall?

We need answers to our financial questions – but they’re now much harder to get.

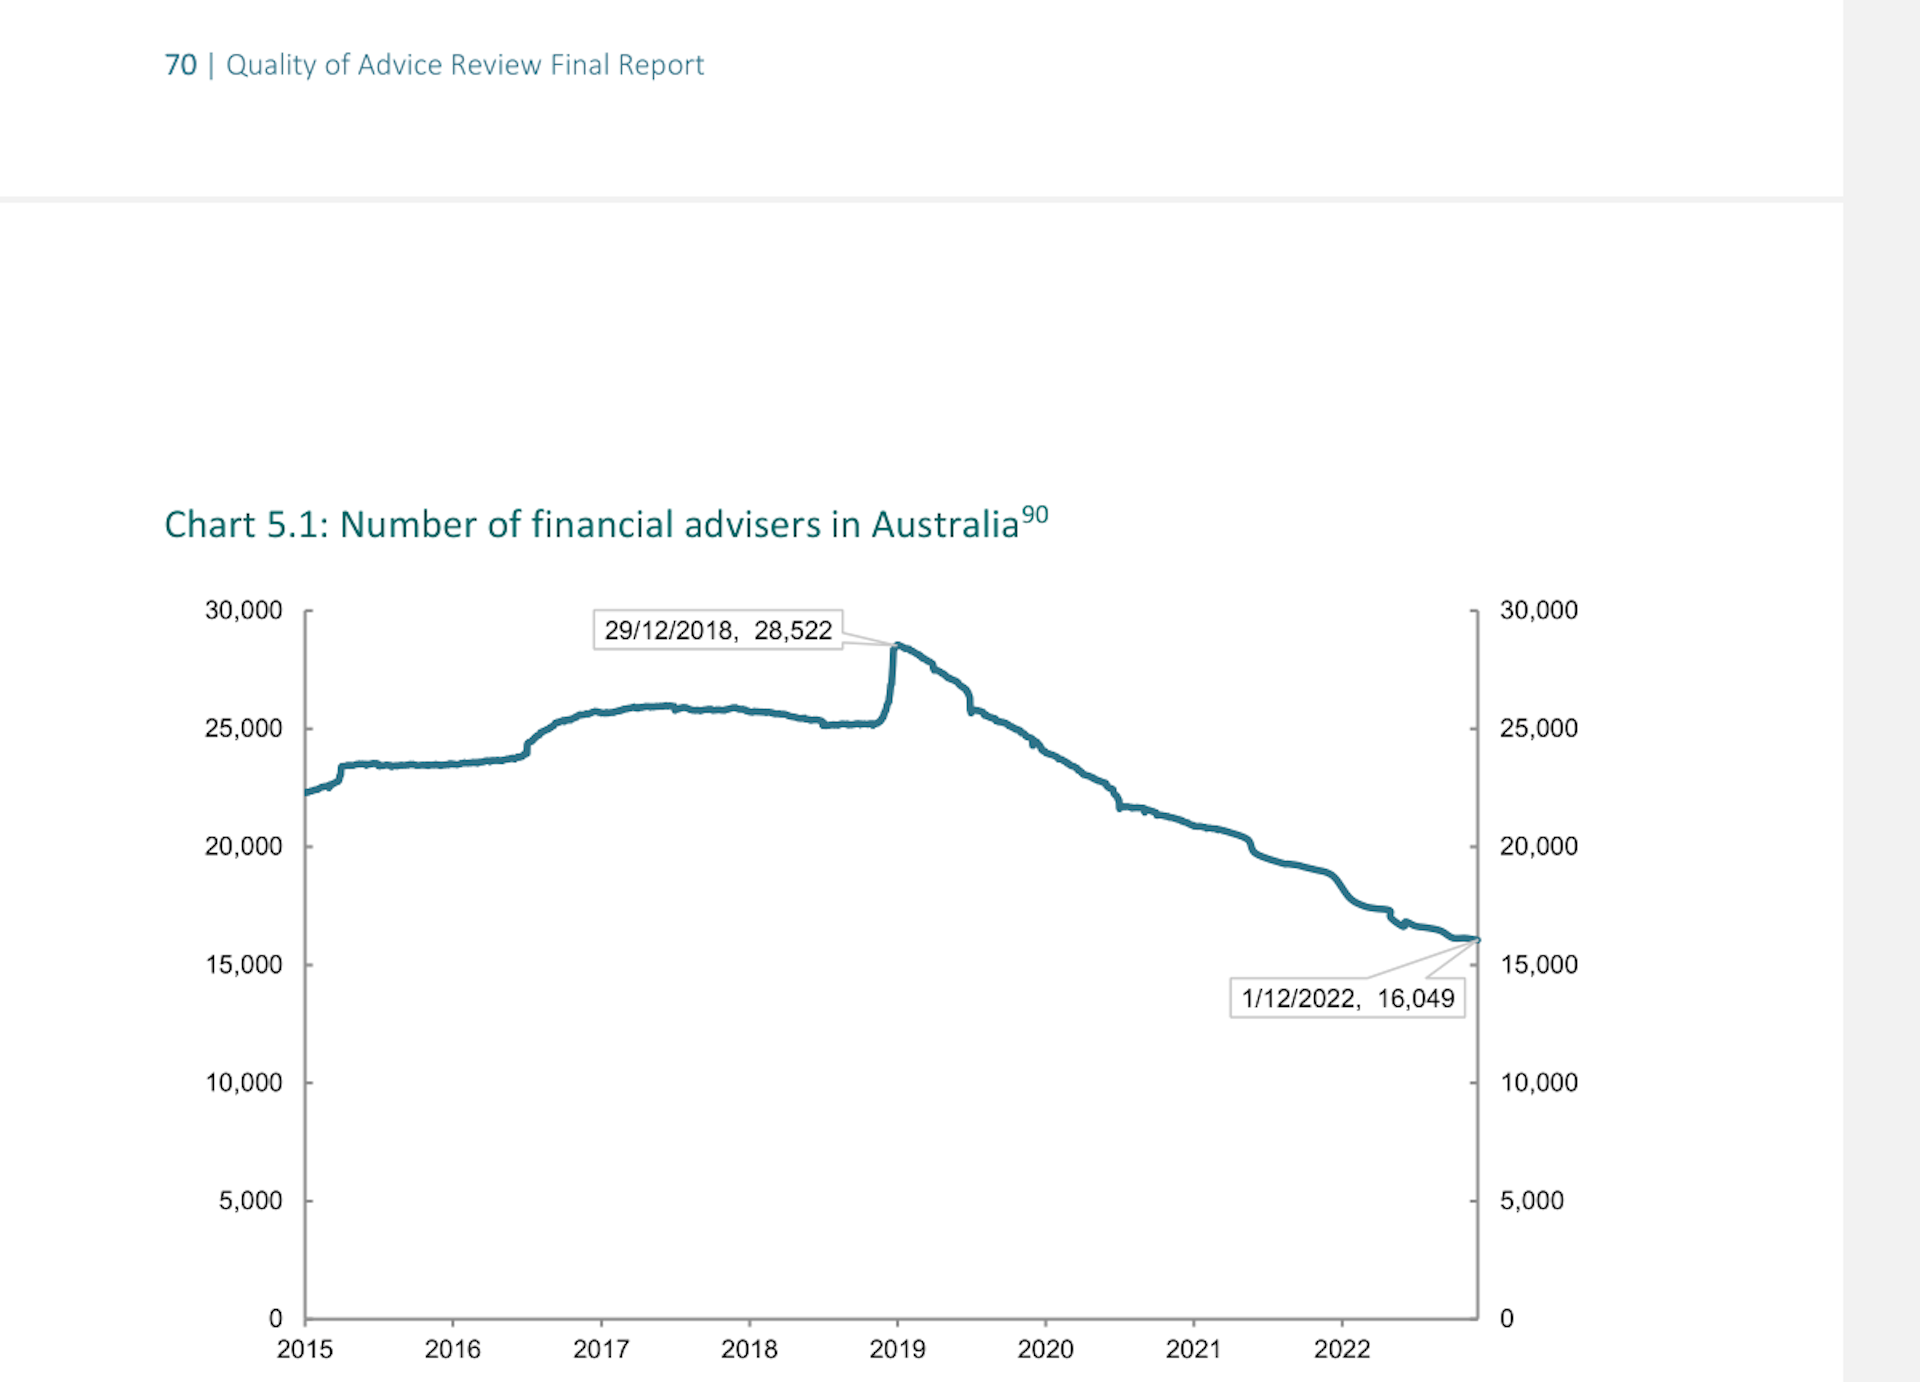
Five years ago, Australia had 28,000 financial advisers. Today there are 16,000. That’s according to a review of financial advice commissioned by the previous government and released by the Albanese government last week.

Thousands of advisers are leaving the industry each year. The ones that remain are charging far more than they used to – $3,710 is said to be common, up 48% in five years, and enough to turn many people away.

So how did it come to this? And what does the new report recommend we do to make it easier for more Australians to get good, more affordable financial help?

Fixing rorts, where even dead people paid a price

This is a story about how Australia, under successive Labor and Coalition governments, let aiming for what’s perfect get in the way of what’s good. Up until I read the Quality of Advice Review last week, I was guilty of doing it too.

For years, I argued we should make financial advice perfect: delivered by genuinely professional advisers, who weren’t receiving kickbacks from firms wanting access to our money. I also argued we should pay for that advice in full upfront, because, whatever the cost, the advice will save us money in the long run.

We needed to do something. Back before a series of explosive Four Corners reports and the 2019 Hayne royal commission into the financial services industry, advisers and the funds they pushed us towards sucked money out of our accounts and presented us with options that made money for them – rather than us.

Read more: Royal commission scandals the result of poor regulation, not literacy

The consequences were shocking. Dead people were being charged for financial advice, and even for life insurance. Gym instructors and other “introducers” were used to lure people into products that charged unnecessarily high fees.

The professionals we now call investment advisers used to be called insurance salesmen. They were paid through commissions to beguile us into signing up for products that charged high fees and paid them high ongoing commissions.

Unintended results of tougher standards

Ahead of the Hayne royal commission, things began to change.

The Rudd Labor government outlawed commissions and introduced legislation requiring advisers to “place clients’ interests ahead of their own”. After winning government, the Coalition tried to undo the changes, before adopting just about the lot after Hayne reported.

It’s now illegal for financial advisers to accept commissions (although mortgage brokers and people who sell insurance still can) and illegal to offer advice that isn’t in the “best interests” of the customer taking almost everything into account. This makes it all but impossible for bank tellers and super funds to offer advice.

So I have been having second thoughts about the arguments I once made for no commissions, best interests, and lots of disclosure documents – especially after reading the Quality of Advice Review. Ironically, its release was largely drowned out by coverage of Australians’ growing financial stress.
The report’s author Michelle Levy is a senior lawyer and expert on superannuation, life insurance, distribution and financial services law. As well as being a partner at Allens, she’s also a parent – and knows more than most how vile predatory financial advisers can be. During the royal commission, we heard about a man with Down syndrome who was signed up for life insurance over the phone, even though he lived on a pension, had no dependants and could not afford the premiums. In her review, Levy discloses that she has a daughter who, “like this gentleman”, lives with a disability and has bank accounts, but does not know the difference between $10 and $1,000, does not know how to use a credit card, or what superannuation is. Levy writes that her daughter ought to be able to rely on her bank and super fund to assist her. She says by stopping firms from providing advice that isn’t perfect, we’ve inadvertently stopped our financial institutions from providing advice that is “good”. We have made it hard for human beings to help each other. Why ‘good’ might be a better benchmark than ‘best’ So Levy wants to allow super funds and banks to offer advice which is “good” but isn’t comprehensive, in the same way as sales assistants are able to offer advice on clothes and mechanics are able to offer advice on cars. Good advice does not mean “okay advice” or “good enough” advice, she says. It is unlikely to be good advice to recommend a poorly performing superannuation product. It will not be good advice to recommend that a person who is unable to pay their mortgage open a term deposit. If the advice isn’t good, the full force of the existing law will come down on the person who provides it (the maximum penalty for an individual is $1.11 million). But it needn’t be comprehensive; not every piece of financial advice needs to be a lifetime plan. What Levy is proposing, and what the government is now considering, is more subtle than what we are doing at the moment – which is simply banning self-interested parties from giving advice. Levy wants to allow the self-interested to give advice, while ensuring it “also serves the interests of their customers”. In the meantime, if you need financial advice, the National Debt Helpline is one of a number of places that can help. You can request a free, confidential meeting with a financial counsellor on 1800 007 007. Read more: Why would you dump a requirement for financial advisers to give advice that's in their client's best interests? Authors: Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

Read more https://theconversation.com/australians-need-good-financial-advice-more-than-ever-to-pay-for-soaring-interest-rates-heres-how-to-get-it-199739

Why the Spring School Holidays Are a Great Time to Visit Coffs Harbour

The spring school holidays are a good time to spend a few days on the Coffs Coast. The weather is starting to warm up, there is plenty to do outdoor...

What to Do When an Older Car Is No Longer Worth Keeping in Melbourne

Ever looked at another repair quote and wondered whether your old car is still worth the trouble? It is a common turning point for Melbourne motoris...

Your Baby's First Year: A Local Guide to Feeding, Sleep, and When to Get Extra Support

Ask ten parents in a Brisbane mothers' group how their baby is feeding or sleeping, and expect ten different answers.  Someone's baby sleeps throug...

Kitchen and Laundry Makeover Ideas That Don't Require a Full Renovation

Full kitchen renos are expensive — and most people don't actually need one.  They need the kitchen to stop looking like it's stuck in 2009, or they...

How Technology Is Reshaping the Modern Australian Commercial Kitchen

The commercial kitchen has always been shaped by technology. Refrigeration changed how ingredients could be stored, modern ventilation transformed k...

The Number on a Roller Blind Fabric That Nobody Explains

Somewhere in the fabric book, next to the colour name, there is a percentage. Three per cent. Five per cent. Ten per cent. Nobody explains it, most c...

What’s Trending in Men’s Jewellery This Father’s Day!

Finding a Father’s Day gift that feels personal, stylish and genuinely wearable is not always easy. While socks and novelty mugs have traditionally ...

Road Signs: Understanding Their Role in Clear and Effective Signage

Effective signage and display hardware can help businesses communicate information, promote products and organise customer or visitor movement. Road...

Bottle Label Printing: Key Factors to Consider Before Your Next Packaging Run

Effective packaging begins with understanding the product, bottle material, artwork and production requirements when planning bottle label printing. H...

Planning a Long-Distance Move With Interstate Movers Melbourne

Moving between states involves more planning than a typical local relocation. Along with packing and transporting household belongings, you need to...

Understanding the Role of an I/O Controller in Industrial Automation

Modern industrial systems depend on accurate communication between sensors, machines and control systems. An I/O controller can help manage this commu...

How the Right Mining Hose Supports Demanding Operations

Mining environments place considerable demands on equipment used for material transfer, water management and processing. Hoses operating in these co...

Simple Ideas for Making Social Gatherings More Memorable

We have all been to those parties where everyone just stands around the kitchen island, staring at their phones, waiting for someone else to make a mo...

Outdoor Wall Lights: Improving Exterior Lighting Around Your Home

Lighting can influence how a room looks, feels and functions, so the right fitting should be selected according to both appearance and practical req...

Commercial Office Cleaning: Combining Routine Office Cleaning With Melbourne Service

Keeping a workplace clean requires a service that can accommodate everyday tasks as well as the particular needs of the business. Professional comme...

Caravan Sales in Queensland: How to Find the Right Caravan for Sale QLD

Caravan ownership is about more than having somewhere to sleep while travelling. For many Queenslanders, it is one of the best ways to explore regio...

What Sir Walter Buffalo Turf Actually Costs in 2026 (And Why Quotes Vary So Much)

Two quotes landed on a Hills District homeowner's kitchen table last spring for the exact same 80-square-metre backyard. One said $12 a metre. The o...

Nearly 1,300 NSW Hospital Beds Are Occupied By People Who Are Ready To Go Home

1,276 people in NSW hospitals have been medically cleared for discharge but remain in hospital because they're still waiting for NDIS or aged care sup...