
NZ’s rising house insurance premiums warn of a system under strain
- Written by: Rohan Havelock, Lecturer, Faculty of Law, University of Auckland, Waipapa Taumata Rau
New Zealand’s Treasury has just launched a review of household insurance affordability – and it could not be timelier.
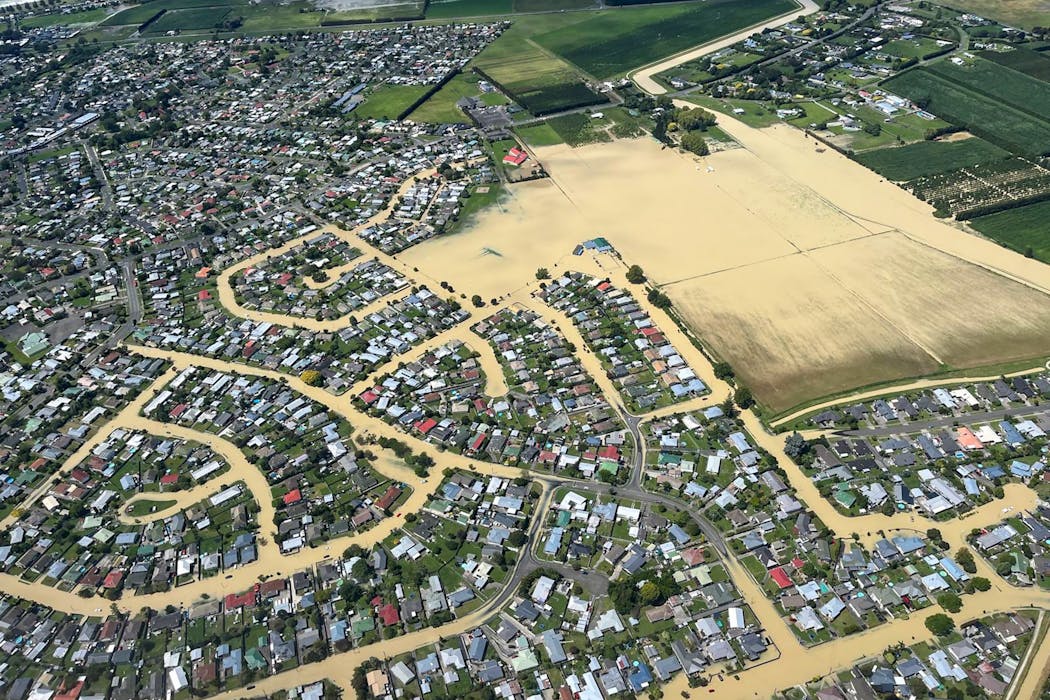
Amid another summer of weather disasters around the country, it emerged one insurer had temporarily stopped offering new home policies in Westport because of flood risk.
This follows wider concerns about insurers retreating from high-risk areas and more than a decade of rising premiums, with costs increasing three times faster than inflation since 2011.
Consumer NZ recently described the situation as “serious” and called for urgent government action, citing concerns about both affordability and the way the market is functioning.
The affordability and availability of private insurance are important public concerns in their own right. But they also have wider significance.
They reflect shifts in the level and distribution of natural hazard risk – and raise hard questions about whether New Zealand’s longstanding model remains fit for purpose.
The system behind the premiums
New Zealand’s approach to natural hazards protection, dating back to World War II, is built on private property insurance. Homeowners who insure privately automatically receive statutory natural hazards cover.
This link between private and public cover sits at the heart of this model. It assumes most households can obtain and afford private insurance. If that assumption weakens, the scheme’s reach shrinks. Access to insurance is therefore not only a market issue, but a structural one.
Essentially, insurance is a way of pricing and pooling risk. When the expected frequency or severity of loss increases, private insurers tend to raise premiums.
Climate change is contributing to more intense rainfall, flooding and landslides in many parts of the country. Past land-use decisions, allowing development in hazard-prone areas, have also increased exposure.
At the same time, New Zealand relies heavily on offshore reinsurance to manage catastrophic risk. In recent years, global reinsurance markets have tightened after large losses abroad. Higher reinsurance costs are often passed on to domestic premiums, along with higher building costs.
Unlike private insurance, natural hazards cover is not priced according to how risky a property is. Instead, it is funded through a flat levy paid by all insured homeowners – currently 16 cents for every $100 of the building cover cap – regardless of whether they live in a low or high-risk area.
This provides a degree of universal protection and spreads the risk of loss among homeowners nationwide, so those in lower-risk areas subsidise those in higher-risk ones.
An unlimited Crown guarantee means that the costs of extreme losses ultimately sit with the public balance sheet. By international standards, this cover is generous and unusual in extending to certain land damage.
Intervening to address the affordability of private insurance – through price controls or mandated coverage, for instance – could have unintended consequences. If insurers are unable to price risk freely, they may withdraw more broadly from certain areas.
Without private insurance, some homeowners would lose access to natural hazards cover altogether. That, in turn, could create pressure to expand statutory cover or rely more heavily on publicly funded disaster relief, shifting greater costs onto taxpayers.
When the safety net is stretched
The pressures facing private insurance are only part of the picture.
The natural hazards cover itself is also under strain. Treasury projects it will be underfunded by about 34% over its first five years, meaning levy income and investment returns are unlikely to cover expected claims over that period.
In practice, underfunding means either higher levies in future – something already signalled – or greater reliance on the Crown guarantee in major events. As hazards become more frequent or severe, that exposure is likely to grow.
The scheme therefore raises not only affordability concerns, but also questions about long-term fiscal sustainability. The Canterbury earthquake sequence illustrated this clearly, exhausting the statutory fund and requiring recourse to the Crown guarantee.
The Natural Hazards Insurance Act, which came into force in 2024, updated and refined the former Earthquake Commission (EQC) regime. It followed a public inquiry that drew lessons from the Canterbury earthquakes, clarifying definitions, lifting caps and improving claims processes.
Yet it did not revisit the system’s core design or its underlying assumptions about natural hazard risk.
For example, the scheme largely treats earthquake, flood (in respect of land damage) and landslide risks the same for the purposes of levies and cover. But these risks are not alike. Earthquakes are typically low in annual probability but high in severity.
Flood and coastal hazards are often more localised, more frequent and increasingly shaped by climate change. Landslides sit somewhere in between. Providing identical cover for very different risk profiles may no longer make sense.
All this underscores the urgent need for a broader review of New Zealand’s natural hazards insurance model. It should draw together hazard and climate science, economic analysis, land-use planning, fiscal sustainability, social policy and insurance market practice.
Rising premiums may be unsettling, but they are a signal of deeper pressures: growing natural hazard risk and strain on New Zealand’s current system.
The real challenge is to decide whether the model we rely on remains fit for purpose and sustainable in the decades ahead.
Authors: Rohan Havelock, Lecturer, Faculty of Law, University of Auckland, Waipapa Taumata Rau
Read more https://theconversation.com/nzs-rising-house-insurance-premiums-warn-of-a-system-under-strain-277088